Nifty flies 10% in a month; smallcaps going nowhere. Which stocks should you buy at this stage?
The Nifty has surged 10% in a month, but smallcaps have barely participated in the rally. Foreign investor inflows, softer crude oil prices and a global rotation away from AI stocks have boosted largecaps. Market experts weigh the valuations, earnings outlook and opportunities across largecap and smallcap stocks.
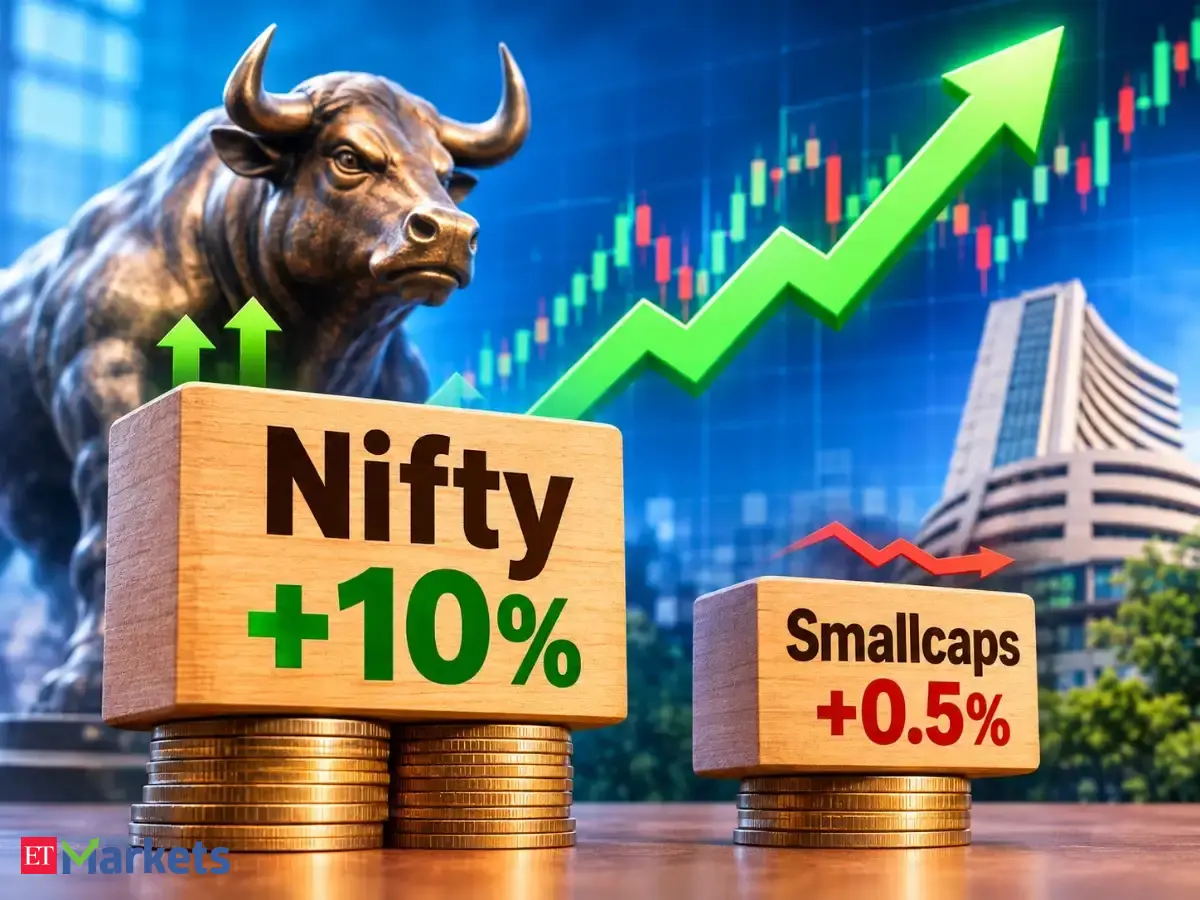
India’s benchmark Nifty has surged 10% in a month, putting it on track for its best monthly performance since 2020. But the rally has a glaring blind spot: smallcaps have largely missed out, with the Nifty Smallcap 250 gaining less than 0.5% over the same period.
The divergence is striking, particularly after a difficult year for Indian equities. Heightened volatility, sporadic recoveries and a sharp correction in benchmark indices kept investors on edge, as a combination of domestic and global headwinds weighed on sentiment. India's longer-term growth story remained intact, but that did little to shield equities from the pressure.
Now, the tide appears to be turning for the market's biggest stocks. A sharp retreat in the AI trade globally, more reasonable valuations and a return of foreign capital have helped put bluechips back in the driving seat. The question is what has changed, and whether the revival can extend beyond the largest companies.
The return of foreign money has emerged as one of the biggest drivers of the rally. Foreign portfolio inflows into Indian equities are on the verge of crossing Rs 1 lakh crore in a single month for the first time.
The turnaround follows one of the most aggressive spells of foreign selling in Indian equities. A Jefferies strategy note said the recent FPI buying of about $11 billion came after two years of outflows that had brought foreign ownership down to 17% in September, its lowest level in 12 years. The note also pointed out that 61% of large emerging-market funds were underweight India.
BNP Paribas highlighted the scale of the recent reversal. Foreign investors bought about $8 billion worth of Indian equities over the 15 trading sessions between October 21 and November 10. That was equivalent to around 16% of their total selling over the preceding two years. The contrast with other Asian markets was stark: investors sold $9 billion in South Korea and $26 billion in Taiwan over the same period.
The shift in foreign portfolios has come alongside a sharp correction in global markets linked to artificial intelligence. BNP Paribas said India is benefiting from a part of the global rotation away from the AI trade, as investors question whether the returns on capital will justify the enormous investments being made and whether AI spending could begin to slow.
V K Vijayakumar of Geojit Investments called the unwinding of the AI trade a "blessing in disguise" for India. He said the retreat from the theme in the US was weighing on markets such as South Korea, Taiwan and Japan, creating an opportunity for India to attract a greater share of global capital.
The easing in crude oil prices and a firmer rupee have provided another tailwind for Indian equities. Brent crude falling below $92 a barrel would further improve India's macroeconomic position, Vijayakumar said.
The rupee has also strengthened against the US dollar, adding to the dollar-denominated returns earned by foreign investors. Together, the currency movement and softer oil prices have improved the backdrop for a market that had been grappling with external pressures.
The preference for largecaps is not simply a consequence of their relative resilience during the correction. Market strategists argue that the segment has undergone a meaningful valuation reset, making large companies more attractive from a risk-reward perspective.
"Large-cap valuations have moderated significantly after nearly two years of relatively flat market performance, improving their risk-reward profile," said Ashutosh Tiwari, managing director and chief investment officer for public equities at Equirus Asset Management.
Tiwari believes largecaps stand to gain the most from any revival in FII flows, given their higher foreign ownership and better liquidity. Equirus currently prefers largecaps, followed by smallcaps, while viewing midcaps as relatively less attractive.
Motilal Oswal expects corporate earnings to grow at a compound annual rate of 15% between FY26 and FY28. The brokerage does not expect a sharp and sustained revival in FII inflows in the near term. However, it believes the combination of earnings growth, macroeconomic resilience and lower valuations has improved the risk-reward equation for Indian equities.
Read more: Covid-era bargains in largecaps, bull market valuations in smallcaps: Where is the real opportunity
Kotak Institutional Equities, meanwhile, believes elevated and rising crude oil prices, the Iran-US conflict and the associated macroeconomic risks have "punctured the euphoria" in the small and midcap space. With valuations in largecaps becoming more reasonable, investors have increasingly found the segment a more compelling proposition.
The September-quarter earnings season has offered some signs of improvement, but investors are becoming more selective. The focus is increasingly shifting towards companies that can deliver sustainable profit growth, rather than those whose valuations were built on aggressive growth expectations.
For Dalal Street, the next big question is whether the return of foreign capital and improving corporate earnings will eventually broaden the rally beyond the largest companies.
There is, however, a strong argument against writing off smallcaps simply because largecaps have taken the lead. Vikas Khemani, founder of Carnelian Capital, believes smaller companies offer the most direct exposure to India's domestic economy.
The smallcap market's value has expanded 2.3 times since April 2023, compared with 1.4 times for largecaps. But Khemani argues that the recent rally in smaller companies should not, by itself, prompt investors to shift towards largecaps.
"Small caps are the most direct way to own the domestic India story," Khemani wrote in a recent investor note.
Carnelian's analysis of 1,594 listed companies found that 59% of smallcap profits come from India's domestic, non-financial economy, compared with 32% for largecaps. Smaller companies also have greater representation in sectors such as healthcare, industrials, consumer discretionary and materials.
The split between largecaps and smallcaps, therefore, is about more than a short-term divergence in market performance. Largecaps currently have the advantage of improving valuations, foreign investor interest and liquidity. Smallcaps, meanwhile, offer a more concentrated play on the domestic economy. Whether the broader market joins the rally will depend on how convincingly earnings growth and investor appetite extend beyond the biggest names.
Related Stories
Leveraged silver speculators wrong-footed by price crash
Investors who borrowed heavily to invest in silver ETFs face steep losses as prices fall 60% from January peak, with high margin trading facility exposure and ongoing interest costs.

Goldman Sachs turns bullish on India stock market, upgrades rating to Overweight; sets Nifty target of 28,500
Goldman Sachs upgraded Indian equities to Overweight and set a December 2027 Nifty 50 target of 28,500, citing expected earnings growth, resilient demand and renewed foreign investment.
Auto, banks power 1,000-point Sensex rally
Benchmark equity indices surged over 1.2% with Sensex nearly 1,000 points higher, driven by strong rallies in auto, consumer durables, and banking stocks, record foreign inflows, and easing commodity prices.