Leveraged silver speculators wrong-footed by price crash
Investors who borrowed heavily to invest in silver ETFs face steep losses as prices fall 60% from January peak, with high margin trading facility exposure and ongoing interest costs.
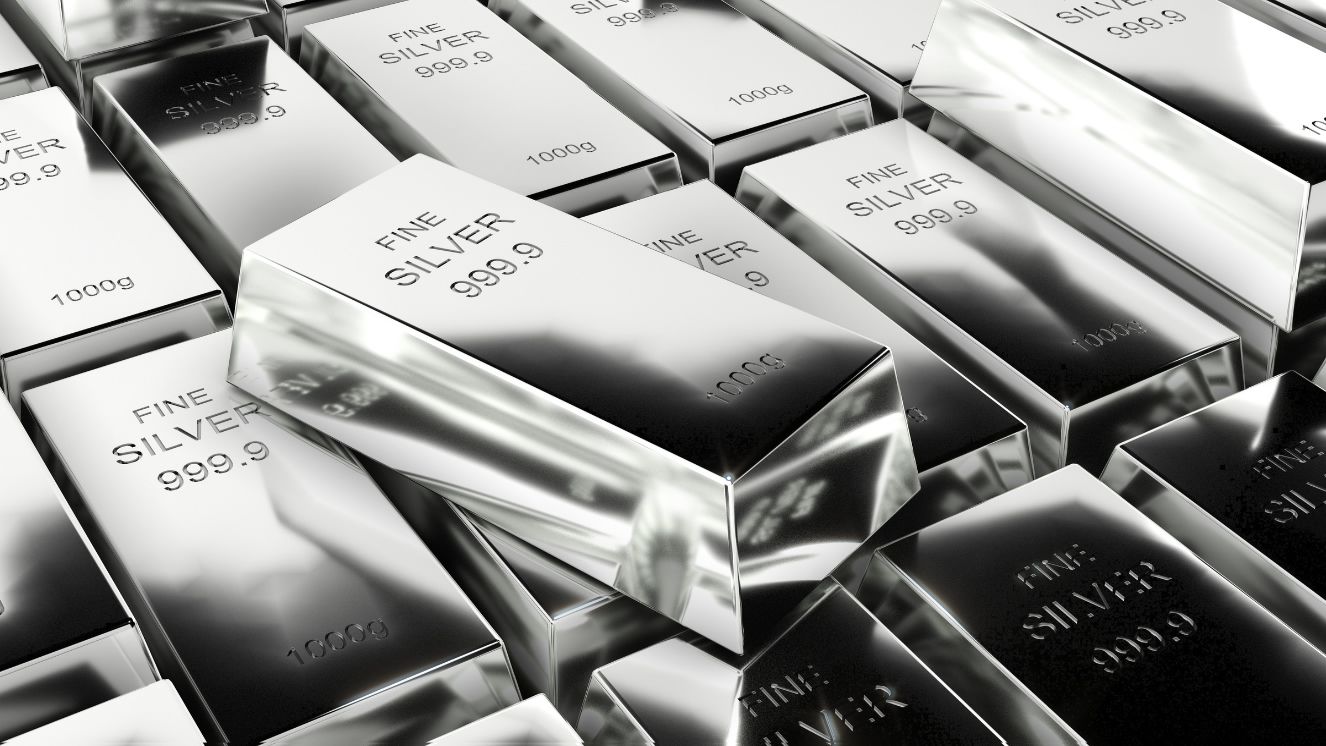
When the chips are down, investors look for a silver lining. But for traders who borrowed heavily to bet on silver, that is proving elusive. With prices plunging 60% from their January peak, many could be sitting on substantial losses while continuing to pay interest on leveraged positions.
The outstanding margin trading facility (MTF) positions in Nippon India Silver BeES, an exchange-traded fund (ETF), stood at Rs 1,058 crore as of November 16, making it one of the most leveraged securities on the National Stock Exchange and BSE.
Only eight major stocks, including Reliance Industries, Jio Platforms and HDFC Bank, had larger MTF books. While blue-chip stocks routinely feature among the most leveraged securities, the presence of a commodity ETF near the top reflects the growing appetite for borrowed bets on precious metals.
MTF allows investors to borrow from brokers to purchase securities, magnifying both gains and losses. Sebi permitted MTF financing for eligible ETFs in 2022, with precious metal ETFs becoming eligible in 2024.
“The money that came in late has taken the heaviest damage,” said Saish Sawant Dessai, commodity research analyst at Emkay Global Financial.
Indian silver ETFs attracted a record Rs 9,463 crore in January, when some units traded at premiums of 10-12% to their underlying silver value. Over the following four months, investors withdrew around Rs 3,770 crore.
“Anyone who bought that rally with a loan had very little room to wait,” Dessai said.
The arithmetic of leverage can be brutal. At five times the exposure, a 20% decline can wipe out an investor’s initial capital. Silver’s correction has been considerably steeper.
“Silver pays no dividend, so the interest on a loan is a certain cost against an uncertain gain,” Dessai warned.
Data from IndiaMTF.com showed that the MTF book in Nippon Silver BeES exceeded Rs 1,760 crore during January’s frenzy. Although positions have subsequently unwound, substantial exposure remains.
“These could be legacy positions. It is like holding on to the tail of the comet,” said Anindya Banerjee, head of currency and commodity research at Kotak Neo.
The rise in outstanding MTF has been extraordinary. In September 2024, MTF exposure in the ETF was barely Rs 45 crore. As bullion prices rallied through 2025, the book swelled to Rs 694 crore by December, coinciding with silver’s surge of more than 150% during the year.
The frenzy was accelerated when several discount and bank-backed brokerages made precious metal ETFs available through instant MTF facilities on trading apps in November 2025. “The convenience matters as the loan is available on tap,” Banerjee said.
That November alone, Rs 536 crore flowed into leveraged positions in Nippon Silver BeES, while Rs 592 crore was withdrawn, highlighting intense speculative activity. “It is like pseudo futures,” Banerjee added.
The attraction is understandable. Unlike commodity futures, ETFs have no contract expiry or mandatory rollover. Investors can purchase small quantities without managing futures margins or meeting minimum contract sizes.
For wealthy investors, borrowing costs can also be negotiated, making leveraged ETF positions an alternative to commodity derivatives. “You are in control and command in terms of ownership of ETF,” said Santosh Joseph, founder of wealth management firm Germinate.
ETFs can also secure capital gains tax treatment, unlike derivatives profits, which are generally taxed as business income. Longer holding periods may qualify for long-term capital gains treatment, subject to applicable rules.
But convenience comes with considerable risks. Falling prices trigger margin calls, requiring investors to provide additional funds or face forced liquidation. Meanwhile, borrowing costs continue accumulating even when the underlying investment loses value.
Sebi’s introduction of dedicated pre-open auctions and dynamic price bands for precious metal ETFs has helped temper speculative activity. Yet the sizeable outstanding MTF book suggests that many leveraged investors remain exposed.
“One cannot say borrowing against ETFs is a smarter and safer route. It is for savvy investors who can make it work,” Joseph cautioned.
For those who bought silver near its peak with borrowed money, the wait for a recovery could prove expensive.
Related Stories

Goldman Sachs turns bullish on India stock market, upgrades rating to Overweight; sets Nifty target of 28,500
Goldman Sachs upgraded Indian equities to Overweight and set a December 2027 Nifty 50 target of 28,500, citing expected earnings growth, resilient demand and renewed foreign investment.
Auto, banks power 1,000-point Sensex rally
Benchmark equity indices surged over 1.2% with Sensex nearly 1,000 points higher, driven by strong rallies in auto, consumer durables, and banking stocks, record foreign inflows, and easing commodity prices.
SEBI plans capacity-building network for independent directors
SEBI is developing a capacity-building network for independent directors to enhance corporate governance amid complex challenges like AI, cybersecurity, and regulatory changes for better transparency and oversight.