Dixon vs Cyient DLM: Why JP Morgan prefers 1 stock after 27% EMS correction
JP Morgan prefers Dixon Technologies over Cyient DLM after a 27% EMS correction.
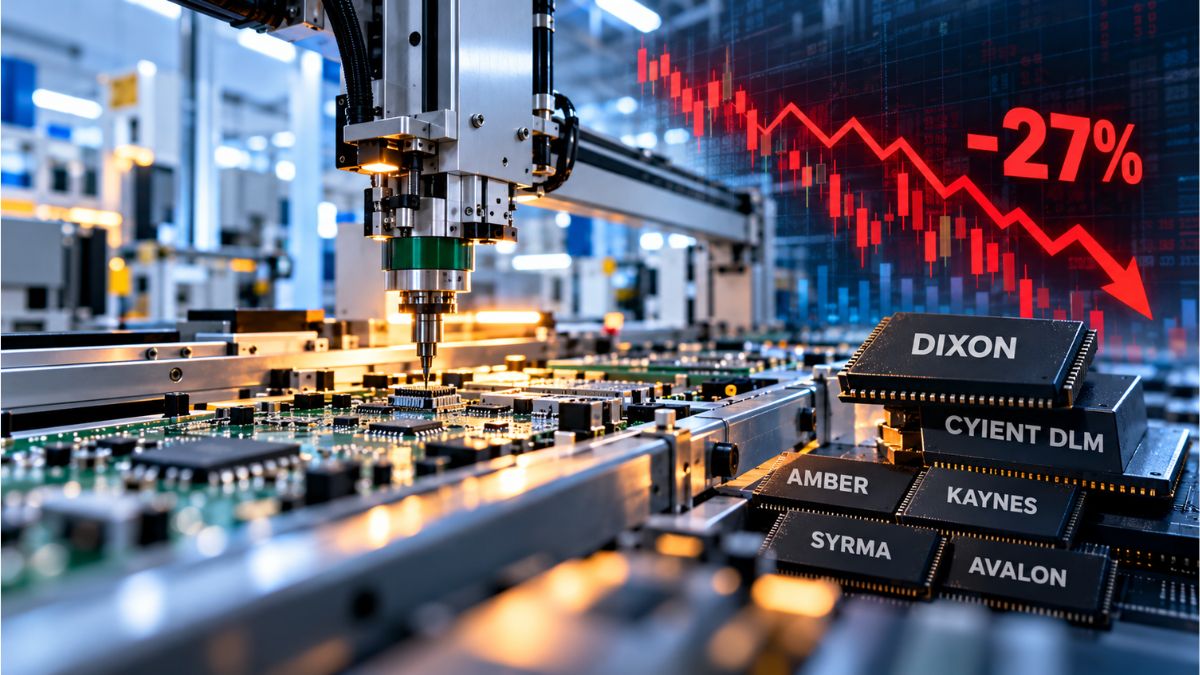
India’s electronics manufacturing services (EMS) stocks have come under pressure after earnings disappointments exposed differences in growth expectations, returns on capital and valuations. In its 20 October 2026 research report, JP Morgan argues that companies in this capital-intensive sector cannot be valued on earnings growth alone.
The brokerage continues to prefer Dixon Technologies and Amber Enterprises India, remains ‘Neutral’ on Kaynes Technology, and rates Syrma SGS Technology, Avalon Technologies and Cyient DLM ‘Underweight’.
Cyient DLM’s earnings miss triggers a sharp correction
According to JP Morgan, Indian EMS stocks fell between 6% and 22% over the month preceding its report, compared with a 2% decline in the Nifty. Among the sector’s year-to-date outperformers, Cyient DLM fell 22%, Avalon Technologies declined 17%, and Syrma SGS Technology lost 10%.
JP Morgan noted that Cyient DLM suffered a sharper fall after its second-quarter results missed expectations on both revenue and margins, while the company also reduced its FY27 margin guidance. The stock dropped 27% over two sessions, even as the Nifty remained broadly flat.
The brokerage linked the size of the correction to the expectations already built into the share price. Cyient DLM had risen 148% year to date before announcing its results, while the Nifty was down 12%. JP Morgan’s 12% reduction in its FY27 earnings before interest, taxes, depreciation and amortisation (EBITDA) estimate was followed by a stock-price correction of more than twice that percentage, which the brokerage attributed to heightened expectations.
JP Morgan also questioned the valuation gap between Cyient DLM and Dixon. Cyient DLM had been trading at a premium despite lower expected earnings growth and ROCE. The brokerage considered that premium unjustified given the difference in the companies’ growth and capital-return profiles.
JP Morgan’s central argument is that earnings growth must be considered alongside the returns a company generates on its invested capital. EMS businesses require substantial capital expenditure and can carry high net working capital (NWC), making the efficiency with which they use capital an important part of their valuation.
JP Morgan stated in its report: “Though P/E multiples are driven by earnings growth in the EMS sector, we believe one has to bake the ROCEs into the multiples as well, given the capex-intensive and high-NWC nature of the sector. Hence, we believe that among companies with comparable earnings growth, the premium multiple should be deserved by the ones having higher ROCEs.”
The brokerage argues that companies with comparable earnings growth should not automatically command similar price-to-earnings (P/E) multiples. In JP Morgan’s assessment, a business generating stronger returns on capital has a better basis for earning a premium valuation than one delivering similar growth with lower capital efficiency.
JP Morgan also identifies three conditions under which the market is likely to pay greater attention to ROCE: an earnings miss, slower growth and persistently high working-capital requirements that weigh on free cash flow (FCF). The brokerage’s view is that when these conditions arise, a company’s ability to convert reported earnings into cash becomes more important to its valuation.
JP Morgan points to the sector’s previous correction as an example of how market attention can turn from growth to cash generation and capital efficiency.
The brokerage wrote: “In our view, the market will start looking at ROCEs once (1) there is a miss on earnings, (2) growth slows down, and (3) NWC remains high, thereby negatively impacting FCF. This scenario played out late last year when EMS stocks had rallied from Jan-Oct ’25 but then Kaynes missed revenue growth expectations and its NWC days also expanded, driving negative cash flows; this shifted the market focus to BS/CF and ROCEs of these businesses, driving a correction in other EMS names also.”
According to JP Morgan, Kaynes’ revenue growth shortfall and rising working-capital days were accompanied by negative cash flows, prompting greater attention to balance sheets, cash flows and returns on capital across the sector. The brokerage connects that period with the correction in other EMS stocks, rather than treating the earnings performance of each company in isolation.
JP Morgan applies the same framework to Cyient DLM. When results fall short of expectations, a stock’s previous gains and valuation can leave less room for disappointment. The brokerage argues that earnings growth alone may not sustain a premium multiple when capital efficiency and cash generation do not provide comparable support.
Dixon Technologies remains JP Morgan’s top pick in the sector, followed by Amber Enterprises. The brokerage compares expected earnings growth between FY26 and FY28 with forward P/E multiples and expected ROCE to assess the relative valuations of the companies under its coverage.
JP Morgan stated: “Dixon stands out, given its higher earnings growth and ROCE and, hence, deserves a premium multiple, in our view.”
In JP Morgan’s assessment, Dixon’s combination of higher earnings growth and stronger ROCE supports its premium valuation. The brokerage’s argument is not that the cheapest stock should always be preferred, but that a premium multiple should be supported by the quality of a company’s growth and the returns it generates on capital.
Amber Enterprises is JP Morgan’s other preferred stock. Both companies carry ‘Overweight’ ratings, reflecting the brokerage’s preference for their combination of earnings growth, capital efficiency and valuation relative to the other stocks in its coverage.
JP Morgan’s stated order of preference is Dixon Technologies, Amber Enterprises, Kaynes Technology, Syrma SGS Technology, Avalon Technologies and Cyient DLM.
The brokerage rates Dixon and Amber ‘Overweight’, Kaynes ‘Neutral’, and Syrma, Avalon and Cyient DLM ‘Underweight’. Cyient DLM ranks last in the stated order following its revenue and margin miss and the reduction in its FY27 margin guidance.
JP Morgan’s assessment rests on the relationship between earnings growth, ROCE and the valuation attached to that growth. Kaynes remains between the preferred stocks and the three ‘Underweight’ names, while the brokerage’s position on Cyient DLM reflects its concerns about the company’s earnings performance, margin outlook and valuation relative to Dixon.
JP Morgan also includes PG Electroplast and Centum in its sector comparison table. However, its stated order of preference covers the six stocks listed above, and the report identifies Dixon and Amber as its top picks.
JP Morgan’s assessment of India’s EMS sector rests on the view that earnings growth cannot be considered separately from capital requirements and returns. The brokerage argues that companies operating in a capital-intensive business need to demonstrate that their growth is accompanied by attractive ROCE and that working-capital requirements do not weigh excessively on cash generation.
JP Morgan continues to prefer Dixon and Amber, remains ‘Neutral’ on Kaynes, and would avoid Syrma, Avalon and Cyient DLM. The brokerage believes Dixon’s higher earnings growth and ROCE support its premium valuation, while Cyient DLM’s earnings miss and reduced margin guidance have exposed the risk of a demanding valuation when expectations are not met.
Disclaimer: This article is based on research reports from one or more brokerage firms and is for informational purposes only. The views, target prices, and recommendations expressed are those of the respective brokerage firms and do not reflect the official policy or position of Financial Express. This should not be construed as an offer, solicitation, or recommendation to buy or sell securities. Investors must conduct their own independent due diligence and seek advice from a SEBI-registered financial advisor before making any investment decisions.
Related Stories

PC Jeweller stock defies market gloom, rises 90% in 2026: Can it hit ₹27 after breaking ₹20 resistance? Expert view
PC Jeweller shares have surged 89% in 2026, reaching a one-year high of ₹20.10. Analysts see potential upside to ₹27 if the stock breaks above ₹20, though overbought indicators could prompt profit-taking.
Sensex, Nifty end lower for third day: Elevated crude, weak market breadth weigh on D-Street
Indian equity benchmarks fell for the third consecutive session on Thursday, October 22, with the Sensex declining 460 points to 73,249 and the Nifty slipping 124 points to 22,688, below the 22,700 mark. Elevated crude oil prices, with Brent above $112 per barrel, weak market breadth and continued underperformance in midcaps weighed on sentiment, while the midcap index hit a six-month low.
HDFC Bank shares down 30% in 2026: FPI love for India’s largest bank wanes; what’s ahead? -
HDFC Bank shares have slumped in 2026 as FII holdings decline and margins remain under pressure. Check Q2 results, brokerage ratings and share price targets.