'Benefit of NSE listing': BSE shares jump 4% as MOFSL upgrades stock to Buy, raises target -
BSE's cash market share improved from 7 per cent to 9 per cent, with NSE's listing and the March 2027 lock-in expiry providing further catalysts, MOFSL said.
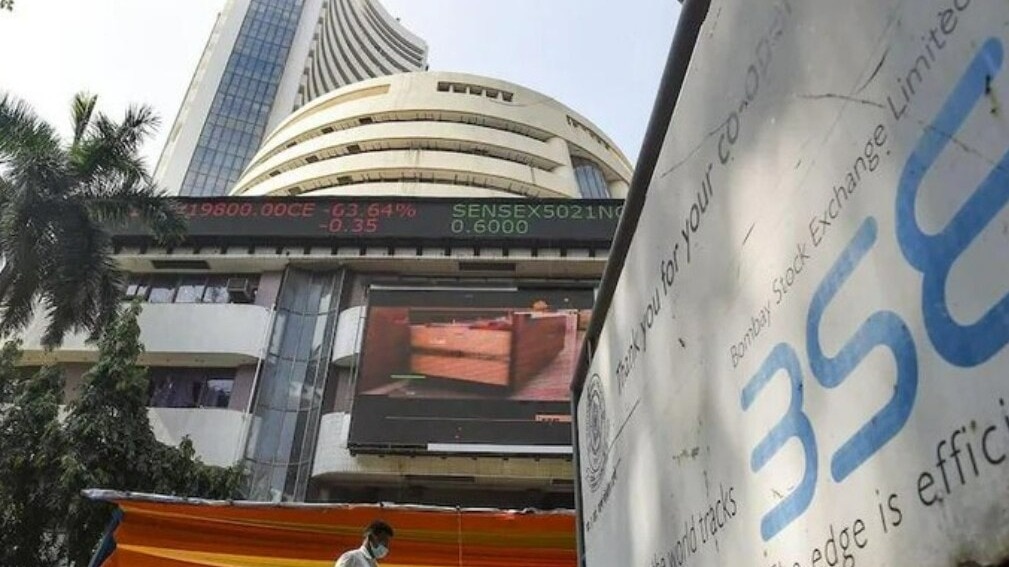
BSE Ltd shares rallied 4 per cent in Monday's trade as MOFSL upgraded the stock to 'Buy', citing a strong volume run-rate, the likely benefit of the Closing Auction Session (CAS) reversal and higher cash volumes following NSE's listing. The domestic brokerage suggested 'Buy' on the stock from 'Neutral' earlier, with a revised target of Rs 4,000 from Rs 3,480 earlier.
On Monday, the stock rose 4.27 per cent to hit a high of Rs 3,369 apiece on NSE. MOFSL said every incremental rupee of BSE revenue has the potential to deliver healthy profit growth, adding that the variable nature of regulatory costs, which account for 55 per cent of operating expenses, provides a degree of insulation against volume slowdowns.
The domestic brokerage said BSE's cash market share improved from 7 per cent to 9 per cent, with NSE's listing and the March 2027 lock-in expiry providing further catalysts. BSE's cash average daily turnover (ADTO) is expected to grow at a 30 per cent CAGR over FY26-FY28.
"Star MF and co-location add scalable, diversified earnings streams," it said.
MOFSL said that since BSE relaunched derivatives in 2023, the impact of most regulatory changes, including F&O 2.0 and the change in weekly expiry day, has been transient. BSE achieved 50 per cent market share in index options notional turnover within three years of the relaunch, while volumes continued to show strong momentum, MOFSL said.
"However, the recent regulatory changes, stricter lending norms for proprietary traders (effective July 2026) and CAS implementation (August 2026), led to a reset in the volume base, with BSE's notional F&O ADTO falling 35 per cent in August 2026 compared with the April-July 2026 average," it said.
Following the base reset in August, September witnessed a modest recovery, with ADTO growing 6 per cent month-on-month (MoM). However, aided by volatile markets, October has seen a significant spurt in volumes, with ADTO up 49 per cent MoM as of October 20, MOFSL said.
"We raise our revenue and PAT estimates by 8 per cent/10 per cent and 10 per cent/12 per cent, respectively, for FY27/FY28. A sustained volume recovery combined with an improving premium-to-notional (P/N) ratio could drive a further 20 per cent increase in FY28E PAT. We upgrade the stock to Buy with a target price of Rs 4,000," MOFSL said.
Related Stories

Around 600% jump in 5 years: Citi maintains 'buy' on Maharatna defence PSU HAL for up to 28% - Check target, rationale
HAL shares have weakened recently, but Citi retained its Buy rating and ₹6,175 target, implying about 28% upside. Citi cited higher inventory and support from engines, helicopters and repairs amid delayed Tejas Mk1A deliveries.
AI relief fails to lift legacy IT stocks as earnings worries weigh
The Indian IT sector has seen a rollercoaster of activity, where mid-sized companies have outperformed their larger peers recently. Increased deal bookings are promising, yet slow revenue growth due to client indecision lingers. The emergence of AI technology brings both new possibilities and pricing pressures for classic services. To sustain their margins in this shifting landscape, companies are honing their operational efficiency.

YES Bank files SC review plea over AT-1 bonds: What does it mean for investors after stock's 15% rebound?
YES Bank has asked the Supreme Court to review its October 15 ruling against the write-down of ₹8,415 crore in AT-1 bonds. The move follows a bondholders’ trustee’s contempt petition seeking restoration of the bonds. The ruling has weighed on the bank’s capital outlook and share price.